
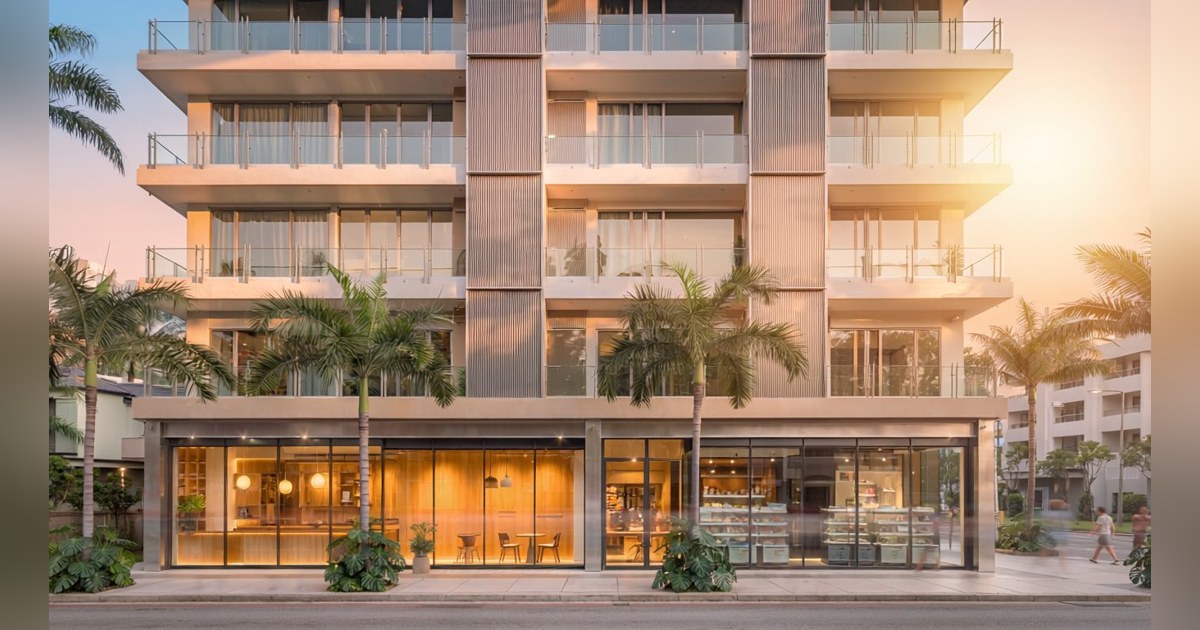
In urban Honolulu, the ground floor of a mixed-use building is increasingly recognized as a major contributor to overall property value, not merely a supplementary income stream. According to Erin W.J. Mitsuyoshi, CCIM, of The Bratton Team at Colliers International Hawaii, well-chosen ground-floor tenants enhance the value of the entire property, making the commercial component a critical factor in both revenue and residential appeal.
The direct financial contribution of ground-floor retail is often stronger per square foot than residential units. Retail rents in well-positioned buildings can exceed residential rents on the same footprint, giving the commercial space disproportionate weight in net operating income. However, this advantage is location-dependent and requires careful analysis rather than automatic assumption. The indirect contribution is frequently larger and harder to model. A grocery store or café downstairs acts as a building amenity, attracting residential tenants without the operating costs of a gym or roof deck. A well-maintained, visually active street frontage also shapes first impressions for prospective residents. At sufficient scale, ground-floor retail can define a neighborhood’s character, which in turn determines who wants to live there. Ward Village, a 60-acre master-planned community in urban Honolulu, exemplifies how a deliberately assembled street-level offer creates a district identity that draws a particular kind of resident to the apartments above.
The tenant categories that succeed under apartments in Honolulu share one characteristic: residents use them regularly, by habit. Daily-needs retail—groceries, convenience stores, cafés, laundromats—anchors the list. Services such as medical offices and childcare also perform strongly. A daycare downstairs is used five days a week by families above, a frequency almost no retail format matches. The composition varies by neighborhood, often reflecting local culture, but the underlying principle is convenience. As Mitsuyoshi puts it, the strongest tenants are the ones where everybody knows your name.
Underwriting mixed-use properties requires separating the residential and commercial components. Unlike standalone retail, a mixed-use building must be bifurcated: each component modeled on its own terms, then combined. Expense allocation is particularly complex. Most commercial space in Hawaii is leased on a triple net basis, so property taxes, utilities, and building expenses pass through cleanly on the retail side. The residential component does not carry those expenses on the same basis, and the two are not equally assessed. Allocating the right percentage to each requires deliberate work rather than a pro-rata split by square footage. Buyers who skip this step tend to misstate both components. Those who do it properly often find the commercial income is more durable than they assumed. Assets of this type appear regularly across current Hawaii commercial real estate inventory.
Tenant selection carries consequences beyond the lease because the ground floor affects the residential component. Compatibility of hours is critical: a late-night use below apartments creates friction, as does noise when residents are home. Proximity to a rail line or major road compounds the issue. A use that unsettles residents can slow residential leasing, while a struggling operator can bring arrears, additional security costs, or parking pressure that spills into residents’ stalls. None of this appears in a rent roll, but it eventually appears in the operating statement. Mitsuyoshi notes these are ripple effects most people never see unless they sit on the ownership or property management side, which is why they belong in acquisition diligence.
The building itself generates only part of the ground floor’s income. Where there are one or two units and the offer is convenience retail, residents filter through constantly. A café draws perhaps once or twice a week; a laundromat weekly; childcare five days. A building with several ground-floor units cannot rely on its own residents alone and must draw from the surrounding neighborhood. That is a solvable design question, but it changes which tenants make sense. For owners, the useful conclusion is that the street level rewards being underwritten properly. Recent closed Hawaii transactions suggest buyers are increasingly pricing it that way.